
Business Writer
The Zimbabwe Revenue Authority (ZIMRA) has engaged stakeholders on the implementation of the Domestic Minimum Top-Up Tax (DMTT), a new tax mechanism designed to protect Zimbabwe’s domestic revenue base and ensure that qualifying multinational enterprises (MNEs) are subject to a minimum effective tax rate of 15 percent.
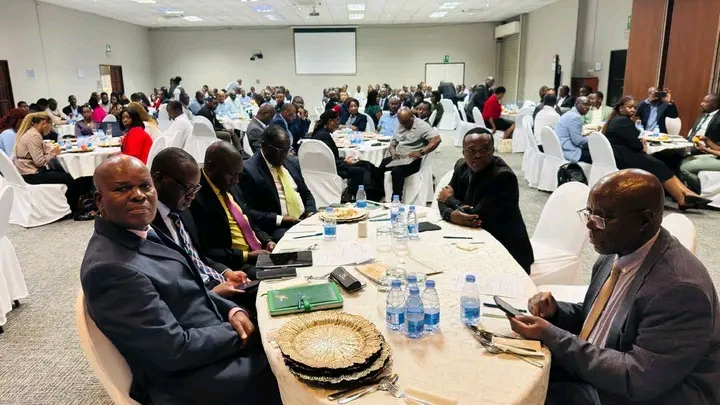
The stakeholder workshop in Harare on Wednesday, 23 September 2026, bringing together representatives from the business community, tax practitioners and other stakeholders to discuss the new tax framework and its implications for affected entities.
DMTT forms part of the broader international effort to address tax avoidance and profit shifting by large multinational groups. Under the global minimum tax framework, jurisdictions can impose a top-up tax where the effective tax rate applicable to qualifying multinational group income falls below 15 percent.
In Zimbabwe, the measure is intended to ensure that where additional tax is due on profits generated locally, Zimbabwe has the opportunity to collect that revenue rather than allowing another jurisdiction to potentially impose the top-up tax.
ZIMRA Commissioner Revenue Assurance Constance Shumbayawonda said the introduction of the DMTT was both a strategic measure to safeguard Zimbabwe’s taxing rights and an economic imperative to protect the domestic tax base in an increasingly interconnected global economy.
She explained that, before the domestic mechanism, a multinational operating in Zimbabwe could potentially face an additional tax charge in the jurisdiction where its parent company is based if its effective tax rate in Zimbabwe fell below the 15 percent global minimum.
“By enacting the DMTT, we ensure that the primary rights to tax the profits generated right here in Zimbabwe remain with Zimbabwe,” Shumbayawonda said, according to reports from the stakeholder engagement.
The framework is linked to the OECD/G20 Two-Pillar Solution, under which Pillar Two establishes a global minimum effective corporate tax rate of 15 percent for large multinational enterprises.
Zimbabwe’s 2026 tax framework provides for a minimum consolidated annual turnover threshold of EUR750 million for the application of the DMTT, targeting large multinational groups rather than ordinary domestic businesses. The 2026 Budget also proposed requirements for affected entities to provide information on their consolidated annual turnover to ZIMRA.
The tax is therefore calculated with reference to the effective tax rate rather than simply the headline statutory corporate income tax rate. ZIMRA’s earlier guidance on DMTT similarly explained that the calculation is based on the effective rate applied to profits generated in a jurisdiction.
Zimbabwe Revenue Authority
The implementation is expected to strengthen Zimbabwe’s ability to retain taxing rights over income arising from economic activity within the country, while bringing the country’s tax administration closer to evolving international standards.
Shumbayawonda said ZIMRA had been building internal capacity to administer the new regime and had trained specialists on the Pillar Two mechanisms. The authority is also working on technical guidance and regulations intended to assist affected businesses with compliance.
The DMTT was enacted through Zimbabwe’s recent tax legislation and applies from 1 January 2026. ZIMRA has indicated that regulations required to operationalise the framework are being finalised.
The stakeholder engagement was therefore intended to give businesses and tax professionals an opportunity to understand the framework, raise technical questions and prepare for the reporting and compliance requirements associated with the new regime.
The introduction of the DMTT represents a significant development in Zimbabwe’s corporate tax administration as the country seeks to balance investment incentives with the need to protect domestic revenue and participate in the evolving international tax system.
Zimbabwe Revenue Authority (ZIMRA).